River & sea flood risk (Flood Zones)
The statutory Flood Zones are the national starting point for flood risk in the planning system. Here’s what Zones 1, 2 and 3 mean, and how we report them for your address.
Flooding from rivers (“fluvial”) and the sea (“tidal”) happens when water overtops a watercourse or coastline and spreads across the natural floodplain. In England this risk is mapped by the Environment Agency as statutory Flood Zones, and it is the first thing planners, lenders and surveyors look at.
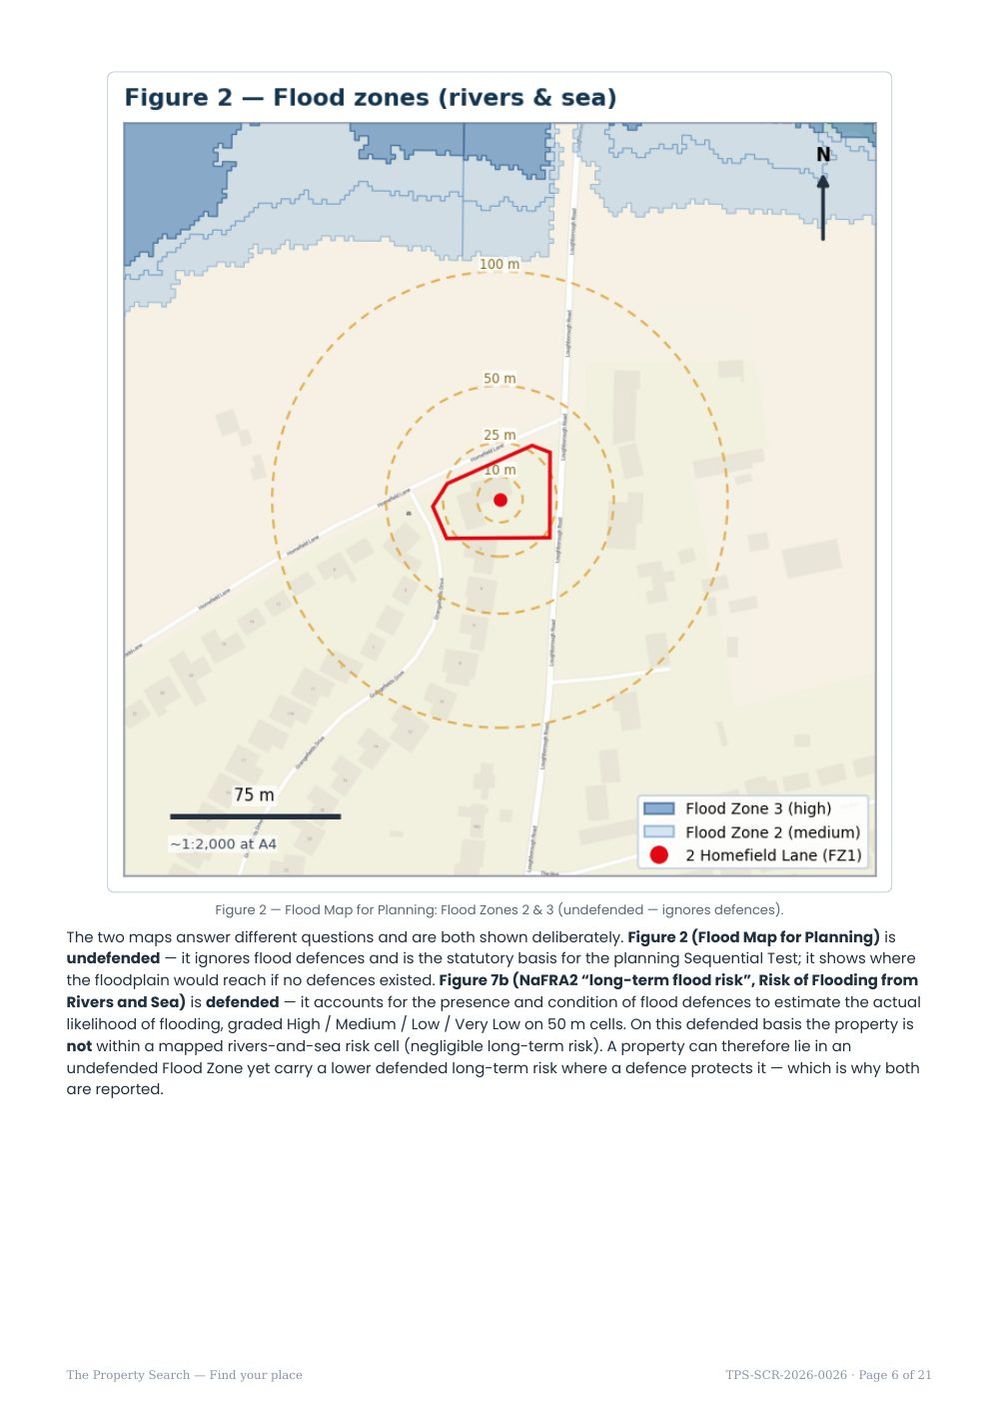
The Environment Agency’s Flood Map for Planning divides all land in England into Flood Zones by the chance of flooding from rivers or the sea, before any defences are taken into account. It is the national reference used across the planning system.
What the Flood Zones mean
A crucial detail: Flood Zones deliberately ignore flood defences. They describe the natural floodplain as if no defences existed, so a defended property can sit in Zone 3 yet be well protected in practice. That is why zoning is a starting point, not the final word.
How we report it
We locate your property against the Flood Map for Planning and report which zone it falls in, plus the distance to the nearest higher-risk land. If the property is in Zone 1 with a floodplain nearby, we say so and give the distance — a nearby floodplain is context, not a statement that the property itself floods. The report includes a map figure showing the property outlined against the surrounding zones.
What it means for you
If you are buying, a Zone 1 result is reassuring but your solicitor should still obtain a regulated flood search. If the property is in Zone 2 or 3, expect lenders and insurers to ask questions, and budget for a possible site-specific assessment. If you plan to extend or build, the local planning authority will use the zone to decide whether a Flood Risk Assessment is required — generally for any site in Zone 2 or 3, or larger sites in Zone 1.
Two maps: undefended and defended
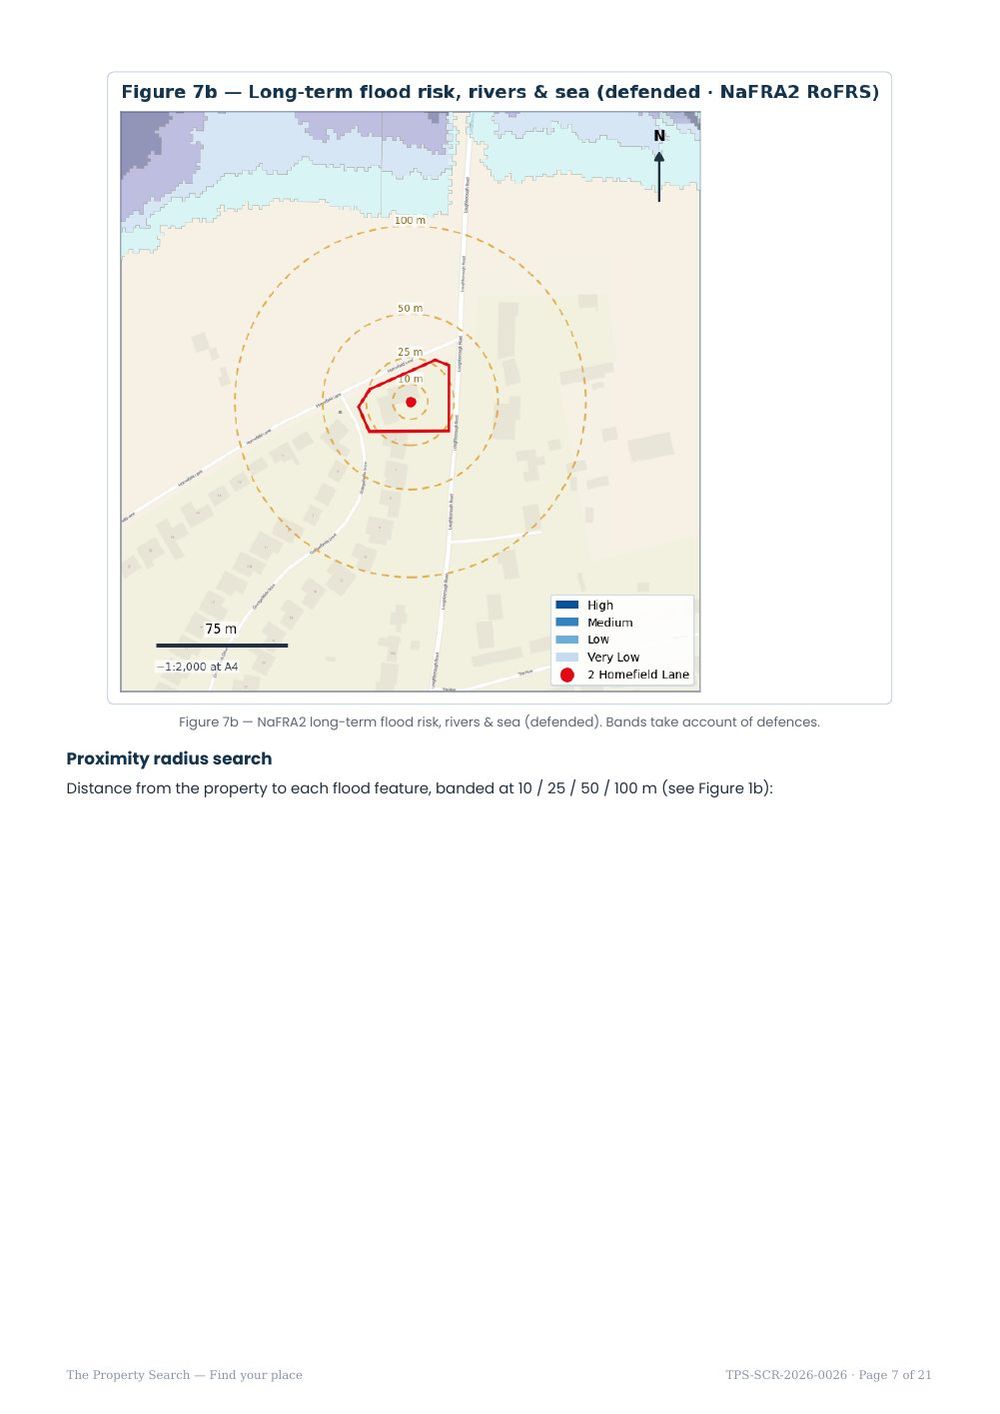
The report shows rivers-and-sea risk twice, because the two maps answer different questions.
A home can sit in Flood Zone 3 yet carry a lower defended risk because a defence protects it. Insurers and lenders often look at the defended picture; planning looks at the zones. Seeing both explains a lot of apparently conflicting answers. The report also gives the distance from your plot to Flood Zones 2 and 3 when it sits outside them.
Know the risks before you commit
An instant, plain-English flood & environmental screen for any address in England — a fast, low-cost first look before you spend on surveys or searches.